


“How much revenue do we need to raise (a Series A)?”
A few years ago, when I started investing, I could have said “get to $1M ARR with good growth and the Series A will materialize.” Storytelling mattered of course, but it was an easy and functional (good enough) approximation to say that if you’re building in a good market, with a good team, and get [this much] traction, the round probably comes together.
Then the bar increased (maybe $2M). Then it went up more ($3M). And now it has just materially changed, rather than merely moved.
Now there really is no answer; it’s a dynamic set of inputs rather than a simple target. Seed investors are supposed to be this bridge to downstream capital and have this answer to shepherd founders but we don’t know, or at least don’t have anything simple/concrete to share.
The outcomes have gotten bigger, the dollars have gotten bigger, the cycles have gotten faster. So early stage is more uncertain and no one wants to be in anything but “the obviously great” thing. Obvious is really key here, and the things that make something obvious are big, fast, and simple.
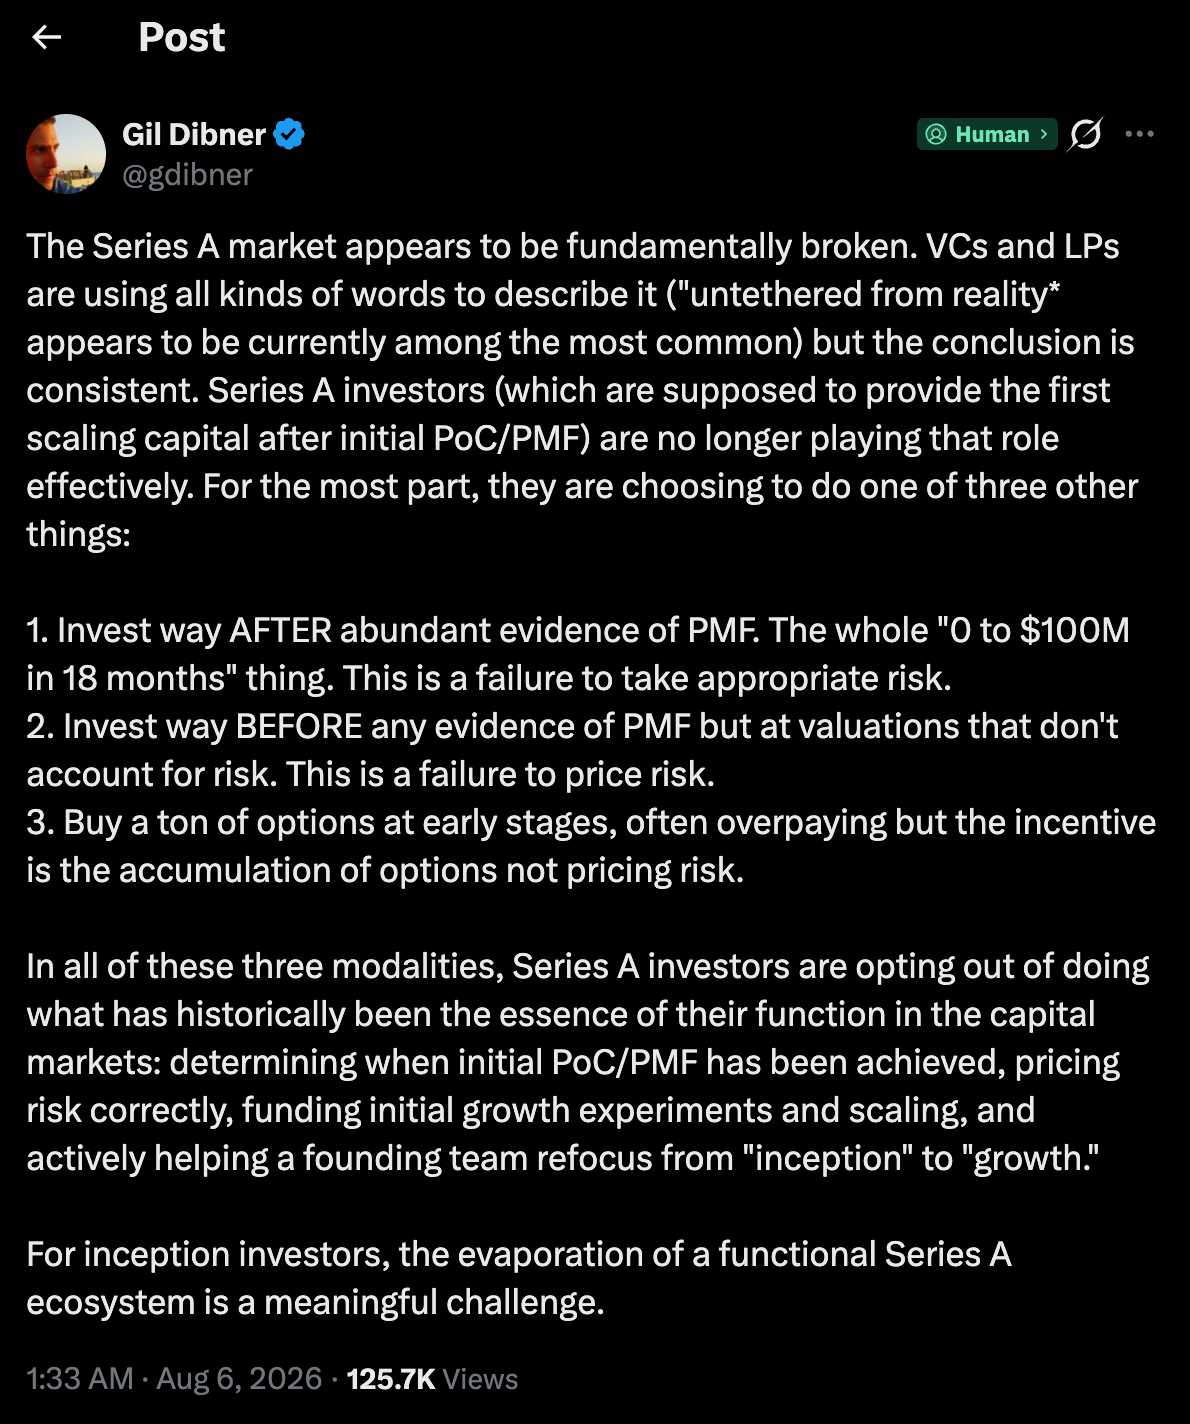
In the simplest terms everyone is looking for expected value (can this be a public company, which really means $20B+ of semi-rational valuation) and category potential (is this a category worth winning). That’s not super useful, or at least not sufficient, in immediate normative terms beyond making sure you’re in an opportunity that can support such an outcome.
After all, the A investor needs to believe you can attract a B. And the B investor needs to believe you can attract a C. And the C investor… No one wants to make that bet when they have infinite dollars and time to sit on the sidelines for the “can’t miss” round.
So - at least when it comes to companies that will raise on the basis of commercial traction at all - this is the rough formula I’ve come up with to explain how the market works and what you need to raise a Series A:
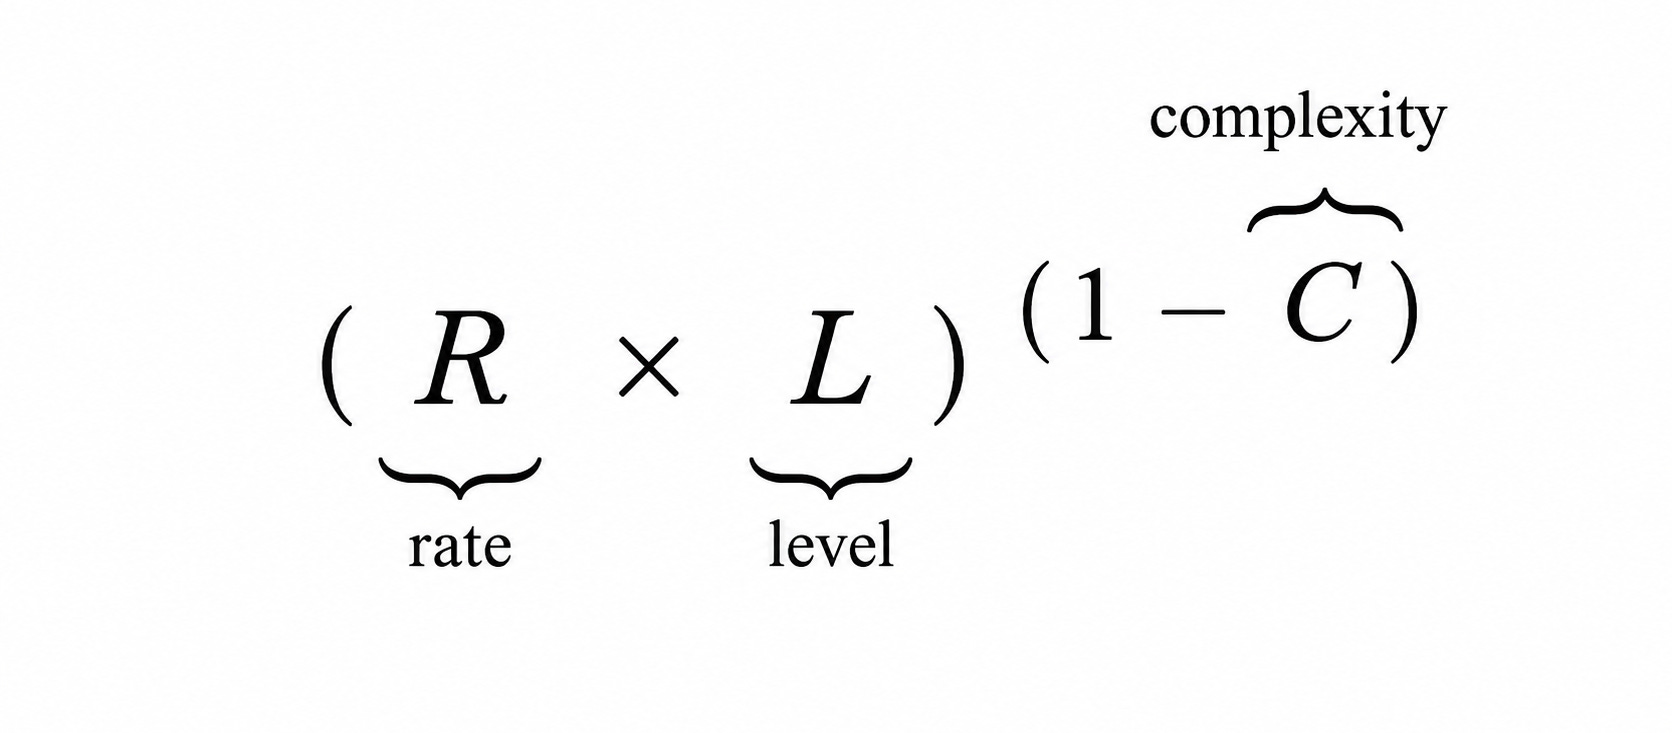
Rates (how fast) and levels (how much) each matter and can compensate for one another. If growth is 0 then great topline doesn’t mean anything. If topline is near-zero, great growth doesn’t mean much.
And the more complex your narrative and story is, the harder it is for people to pay attention to the momentum. Simple, powerful stories let great numbers shine. Complex stories are drags on the internal proof/momentum/traction you’ve created.
The more logical leaps you have to take in either explaining what you are (this is why people like X for Y framings) or explaining what you’re doing (this is why people like “we went N to M in Z months” to understand traction) the harder your job becomes and the less compelling the story is overall. As soon as you’re justifying the size of your opportunity, you’ve probably already lost. The simplest stories are the ones we’ve all already agreed on.
The bar to clear will move around in time and from investor to investor, but this is the rough measuring stick.
The normative advice here is really about framing yourself as simply as possible with the goal of becoming a financial earworm, meme, or cognitive virus. And of course, grow.
Addendum
For someone out there there’s a great opportunity to lead $8-15M Series As and basically get your choice of every asset in that category, if you can either 1) underwrite the rest of the market waking up to it later or 2) have some measure of capital independence (not necessarily FCF+).